Networthfy is an independent financial comparison platform. We may earn a commission when you click through.
Personal Loan Rates: The NZ$1,722 to NZ$51,111 Spread
Across 11 NZ personal-loan listings, average advertised rates span 11.23% to 19.43% p.a.; fees and credit rules change the result.
The listings span an average loan range of NZ$1,722.22 to NZ$51,111.11, while average advertised rates run from 11.23% to 19.43% p.a. That gap matters more than a lender's headline starting rate: a low minimum may come with stricter credit rules, an establishment fee, or a much higher personalised rate.
Rates and terms shown are representative. Your actual rate depends on your credit profile and circumstances. This is not financial advice — always read the lender's terms before applying.
APR Range
The biggest loan is not automatically the cheapest
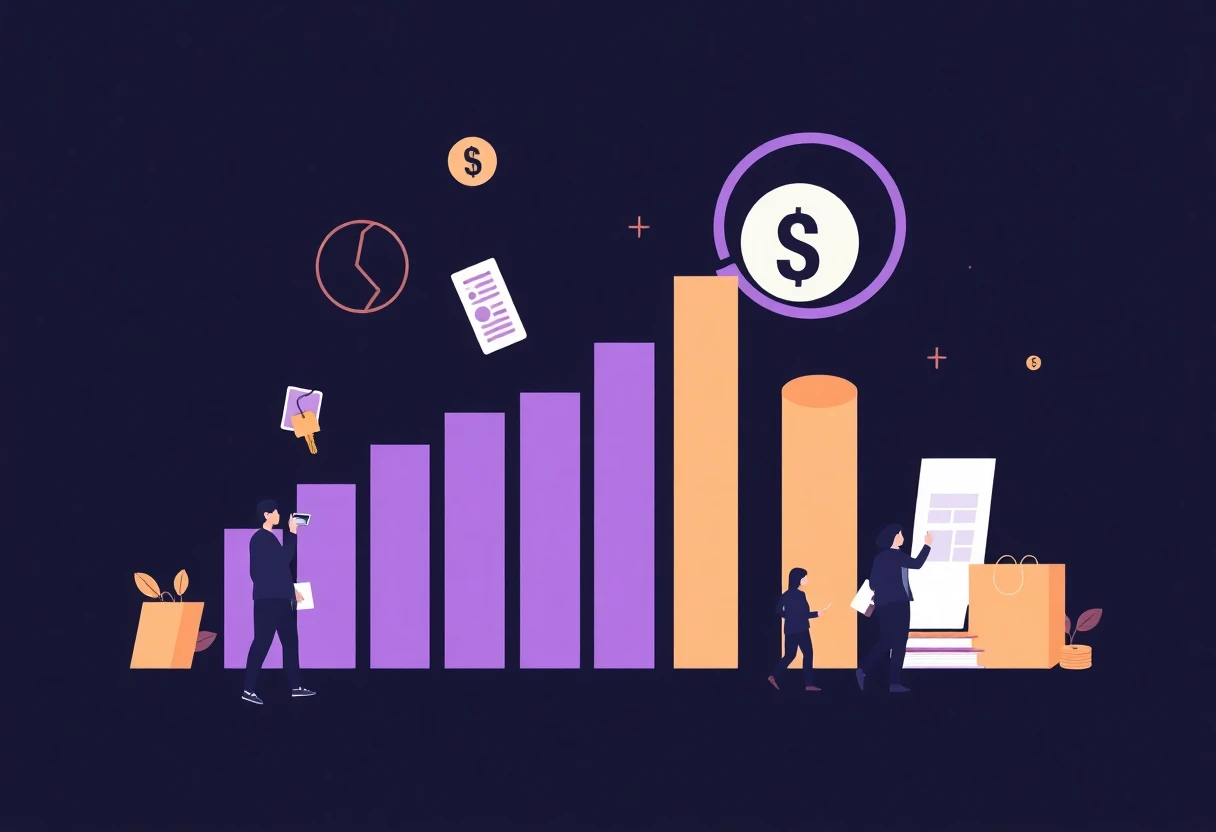
As the chart shows, the listings cover a wide borrowing spread. That does not prove that larger loans receive lower pricing per dollar; the supplied aggregate data contains no loan-by-loan APR, amount, credit-tier, approval-time, or repayment-cost pairing. Treat any claim that larger loans are cheaper as unverified until a lender gives you a personalised quote.
Use the range as a screening tool. Borrow only the amount required, then compare the total repayment and every fee at the same term. A NZ$150 establishment fee on a NZ$2,000 loan has a much larger effect than on NZ$50,000, even before interest is added.
Lowest advertised APRs, with conditions attached
Harmoney has the lowest listed starting rate at 7.99% p.a., but the rate is personalised, a NZ$150 establishment fee applies, and applicants must have no defaults on their credit file, according to the Harmoney personal-loans page. The Co-operative Bank starts at 9.95% p.a. and charges no early-repayment fee, though pricing depends on your credit rating.
Westpac also lists 7.99%, but that rate is specifically for electric-vehicle purchases; its standard rate is 13.90% p.a., according to the Westpac loan listing. Instant Finance starts at 9.95%, but its range reaches 29.95% and includes a NZ$100–NZ$220 establishment fee plus NZ$3 per instalment.
Harmoney Personal Loan
Harmoney has the lowest advertised starting rate in this group at 7.99% p.a. and allows borrowing from NZ$2,000 to NZ$100,000, with an online quote flow that can take as little as nine minutes without affecting your credit score. The headline rate is not guaranteed, the NZ$150 establishment fee reduces the benefit on smaller loans, and defaults are not accepted. Best for a borrower with no defaults, good income documentation, and a need for a fully online application.

The Co-operative Bank Personal Loan
The Co-operative Bank starts at 9.95% p.a., below the listing aggregate's 11.23% average minimum, and has no early-repayment fee. Its nine consecutive Canstar Outstanding Value Awards add useful context, but the rate still depends on credit quality and the smaller branch network may matter if you prefer face-to-face service. Best for a borrower with good credit who values a low rate and the ability to repay early without a penalty.
ASB Personal Loan
ASB starts at 12.90% p.a. and permits terms up to seven years, which can reduce the required payment but increases the time interest can accumulate. Compared with Harmoney, the starting rate is higher; compared with ANZ, the longer maximum term gives more repayment flexibility. Best for an existing or prospective ASB customer who needs a longer term and can afford the resulting total cost.
ANZ Personal Loans
ANZ uses a fixed 13.90% p.a. standard rate rather than rewarding excellent credit with a lower tier, but it lists no application, early-repayment, or repayment-change fees. Approval can take up to five business days, so the lender is less suitable for an urgent expense than Harmoney's online quote process. Best for an existing ANZ customer who prefers predictable pricing and a fee-free structure over the lowest possible rate.
Those four listings show why APR alone is not enough. Harmoney wins on the starting number, the Co-operative Bank offers a strong bank alternative, ASB stretches the term, and ANZ removes several listed fees. The right comparison is the same loan amount, same term, same repayment frequency, and the actual rate offered after assessment.
Bad credit and fast approval: what the data can and cannot say
Bad credit is not proven to be an automatic barrier across this set, but the supplied figures do not include rates by credit tier. Harmoney explicitly requires no defaults, while the Co-operative Bank says pricing depends on credit rating. That is enough to reject any promise that a low advertised rate will be available to every applicant.
Approval speed is also incomplete. Harmoney's quote can take as little as nine minutes without affecting your credit score; ANZ says a decision can take up to five business days; SBS lists processing of one to three days. Those are not directly comparable measures, because a quote, a decision, and funded money are different stages. Ask each lender when funds arrive, not merely how quickly an application starts.
SBS Bank Personal Loan
SBS Bank lists a relatively tight 11.50%–15.50% rate band, which gives more pricing visibility than a lender showing only a low starting rate and a high ceiling. Processing is listed at one to three days, and the maximum loan is NZ$30,000. Best for a borrower who wants a customer-owned mutual bank, a defined rate range, and does not need the largest borrowing limit.
Instant Finance Personal Loan
Instant Finance accepts applications from NZ$500, the lowest minimum shown here, but the advertised range reaches 29.95% and fees include NZ$100–NZ$220 upfront plus NZ$3 per instalment. That combination can make a small loan expensive, even if the starting rate is 9.95%. Best for a borrower who needs less than NZ$2,000 and has checked the full repayment total rather than focusing on the minimum rate.
Kiwibank Personal Loan
Kiwibank starts at 12.99% p.a. and caps the listed loan amount at NZ$30,000, below Harmoney's NZ$100,000 maximum and alongside SBS's NZ$30,000 ceiling. The appeal is its locally owned banking model, but the listing does not provide a faster approval promise or an online-only discount. Best for a borrower who prefers a New Zealand-owned bank and needs no more than NZ$30,000.
Westpac Personal Loan
Westpac's standard listed rate is 13.90% p.a., but electric-vehicle purchases qualify for a 7.99% special rate. That makes the offer highly purpose-dependent: it competes with Harmoney only for the stated EV use, not for a general personal expense. Best for an EV buyer who wants a major bank and has confirmed the special-rate eligibility before applying.
What to do before applying
- Set one comparison case. Use the same amount and term with every lender, then compare total repayment, not just APR.
- Ask about the assigned rate. Harmoney's 7.99% and the Co-operative Bank's 9.95% are starting rates, not promises for every applicant.
- Price the fees against the loan size. A fixed establishment fee matters far more on a small loan.
- Check credit rules first. A no-default requirement can end an application before the advertised rate becomes relevant.
- Separate approval from funding. Harmoney's fast quote, SBS's one-to-three-day processing, and ANZ's possible five-business-day decision describe different stages.
The data supports a clear shortlist, not a universal winner. Harmoney is the rate and speed leader on the information supplied, but only for applicants who meet its credit rules and accept the establishment fee. The Co-operative Bank is the more balanced rate pick for good-credit borrowers who value no early-repayment fee. Instant Finance fills the small-loan gap, while ANZ suits existing customers who want fee clarity rather than the lowest headline rate.
For a wider comparison of rate, approval speed, and repayment flexibility, read Top Personal Loans for 2026: Rates, Speed, and Flexibility Compared.